The Ledger · Trades
Break-Even Point Formula: How Many Jobs a Month Clears the Nut
Break-even point = fixed costs divided by contribution per unit; on the workbook's seed figures a $4,780 monthly nut and $540 of contribution per job break even at 7.77 jobs a month.
The break-even point formula is fixed costs divided by what one sale contributes: fixed costs ÷ (price − variable costs). In a jobs business the unit is a job, so on the workbook’s seed figures a $4,780 monthly nut against $540 of contribution per job breaks even at 7.77 jobs a month. That is roughly one job every 2.70 working days.
Most explanations of this formula sell garden benches. Nobody who runs a service truck sells benches, and “units” is the word that makes an owner close the tab — which is a shame, because the arithmetic is the single most useful thing in small-business finance and it takes about four minutes. Below is the formula, then the same formula run on a real repair contractor’s seed numbers, in jobs, on a calendar, and finally the part almost nobody mentions: break-even is not the month you stop being broke.
Every dollar figure below is a seed value from the Contractor Break-Even & Cash Model‘s THE NUT and SIX-MONTH CASH sheets, with its cell reference, and you can put your own numbers through the same formulas in the free contractor break-even calculator.
What is the break-even point formula?
Break-even in units is fixed costs divided by the contribution each sale makes, where contribution is the price minus the costs that only exist because you took that sale.
That is the canonical form, and it is the one the U.S. Small Business Administration publishes for a business plan: Fixed Costs ÷ (Price – Variable Costs) = Break-Even Point in Units (retrieved 2026-09-28). Two sibling forms fall out of it, and between the three of them you can answer any version of the question.
contribution per unit  =  price - variable costs
contribution rate      =  contribution per unit / price

break-even in UNITS    =  fixed costs / contribution per unit
break-even in DOLLARS  =  fixed costs / contribution rate
margin of safety       =  (actual - break-even) / actual
The trap is in the word fixed. Fixed costs are not just the bills; they are everything that keeps arriving in a month when you sell nothing, and for an owner-operator that has to include what you need to take home. Leave your own pay out and the formula cheerfully reports a break-even you can hit while starving.
How do you run it when you sell jobs instead of units?
The job becomes the unit. Take your average ticket, subtract the hard costs that only happen because that job happened, and divide the monthly nut by what is left.
Here is the chain exactly as the workbook runs it on its seed figures. The average repair ticket is $900. Hard costs on that job are $360 (F10), so contribution per job is $540 (F12) and the contribution rate is 60.0% (F13). A 10% house fee of $90 (F11) comes off after that, leaving $450 net per job (F14) and a 50.0% gross margin once overhead is counted (F15).
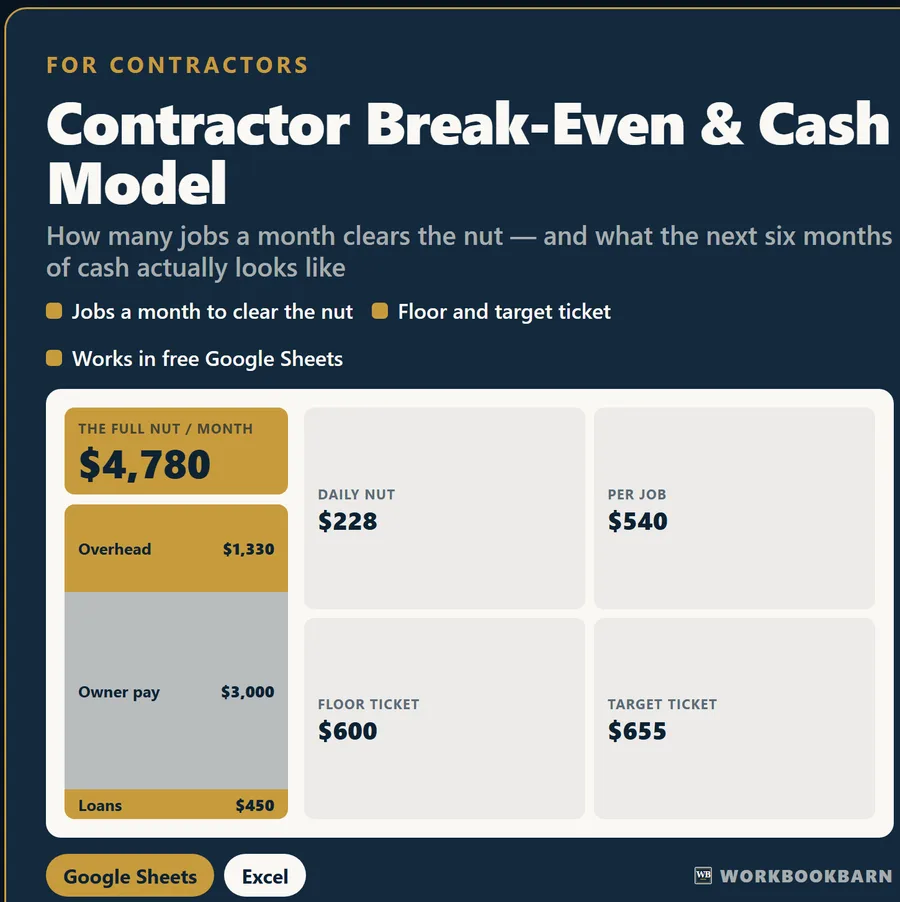
On the cost side the model carries two different numbers, and the difference between them is the whole point. Fixed overhead — the sum of nine line items — is $1,330 (F5). The full nut is $4,780 (F6), because the nut is what the month actually has to produce, not what the bills add up to. Divided across 21 working days that is a daily nut of $227.62 (F7).
| What it is | Cell | Value |
|---|---|---|
| Average ticket | — | $900.00 |
| Hard costs on the job | F10 | $360.00 |
| Contribution per job | F12 | $540.00 |
| Contribution rate | F13 | 60.0% |
| Fixed overhead (nine lines) | F5 | $1,330.00 |
| The full monthly nut | F6 | $4,780.00 |
| Recurring retainer contribution | F27 | $585.00 |
| Jobs to cover overhead alone | F28 | 1.38 |
| Break-even jobs a month | F29 | 7.77 |
| Break-even revenue | F30 | $7,891.67 |
| Working days between jobs | F31 | 2.70 |
| Margin of safety | F33 | 22.3% |
Two things in that table are worth slowing down for. First, 1.38 jobs (F28) covers the overhead on its own — the bills are the easy part. It takes 7.77 jobs (F29) to cover the nut, and the gap between 1.38 and 7.77 is what the owner has to be paid. Second, this model has $585 a month of retainer contribution (F27) arriving before any job is sold, so the break-even count is (nut − retainers) ÷ contribution: (4,780 − 585) ÷ 540 = 7.77. Recurring revenue does not just smooth the month; it moves the finish line closer.
What does 7.77 jobs a month look like on a calendar?
It is one job every 2.70 working days, or about two a week. That conversion is the reason to do this at all, because a monthly count is not something you can act on this morning.
The workbook does it as 2.70 working days between jobs (F31) — 21 working days divided by 7.77 jobs. Read against the $227.62 daily nut (F7), that is the sentence a schedule can answer: every working day costs $227.62 whether a truck moves or not, and a $900 ticket buys you just under four days of breathing room. A three-day gap is not slow, it is a $683 hole.
Break-even also fixes what you are allowed to charge. On these seed figures the floor ticket is $600 (F19) and the target ticket is $654.55 (F20) — the same $360 of hard cost priced to a 30% margin floor and a 35% target with the house fee counted. Quote under the floor and no amount of volume fixes it, which is the same arithmetic as why a 40% markup is only a 28.6% margin.
Is there a break-even formula for Excel or Google Sheets?
Yes, and it is one cell. Put the nut in one cell, contribution per job in another, and divide — no add-on, no solver, no subscription required.
This is literally what the workbook’s break-even cell contains, in the plain arithmetic both Excel and free Google Sheets understand:
F12:  =900-360                 contribution per job      -> 540
F13:  =F12/900                 contribution rate         -> 60.0%
F29:  =(F6-F27)/F12            break-even JOBS a month    -> 7.77
F31:  =21/F29                  working days between jobs  -> 2.70
F33:  =(10-F29)/10             margin of safety at 10 jobs -> 22.3%
No XLOOKUP, no LAMBDA, no dynamic arrays. That is deliberate: the same file has to open in Excel and import into free Google Sheets, so the whole workbook is written in an older formula vocabulary. If you want the one-line version with nothing recurring, drop the retainer term: =F6/F12, which on these numbers gives 8.85 jobs instead of 7.77.
What is a good break-even point?
There is no good number in the abstract. What matters is the distance between break-even and what you actually sell, and that distance has a name: margin of safety.
Run this plan at ten jobs a month and the ledger’s own figures fall out: a 22.3% margin of safety (F33), from (10 − 7.77) ÷ 10. Monthly contribution is $5,985 (F36) — ten jobs at $540 plus the $585 of retainers — and after the $4,780 nut that leaves $1,205 of monthly profit (F37). Over the model’s full twelve months the DASHBOARD averages 11.92 jobs a month (E5) as the ramp fills in.
22.3% means roughly one job in five can vanish before the month goes red. That is a thin cushion, and it is the honest read on a business running two jobs a week against a $4,780 nut. The lever is not always “sell more”: raise the ticket, cut a line out of the nut, or add retainers, and the break-even count drops without a single extra job.
Why are you past break-even and still out of money?
Because break-even is an accounting line and cash is a calendar. You can cross break-even on paper months before the bank account stops falling, and the gap is where businesses die.
The SIX-MONTH CASH sheet shows the shape. Month one turns $3,520 of job revenue (E5) against $1,408 of direct costs (H5) for a net of −$5,118 (J5). Month two nearly gets there — $6,900 of revenue (G6), a net of only −$610 (J6) — and yet that is the month cash bottoms out at −$2,728 (K6). Net turns positive in month three at $1,026 (J7). By month six cash on hand is $5,954 (K10), and at twelve months $44,513 (K16). The dashboard’s summary of that journey: two months in the red (E14), lowest cash −$2,728 (B14).
So the number that actually needs funding is not the break-even count, it is the trough. This is not an unusual problem either: in the Federal Reserve Banks’ 2025 Report on Employer Firms, 56% of firms cited paying operating expenses and 51% cited uneven cash flows as financial challenges (Small Business Credit Survey; retrieved 2026-09-28). Break-even tells you the target. The trough tells you how much you need in the account to survive reaching it.
Common questions
What is the break-even point, in one sentence?
The sales volume at which total revenue equals total costs — the point where you stop losing money and have not yet started making any. Expressed in units it is fixed costs divided by contribution per unit; expressed in dollars it is fixed costs divided by the contribution rate.
Should my own pay be a fixed cost?
If you are the one doing the work, yes — otherwise the formula reports a break-even you can hit while taking home nothing. The workbook makes this visible by carrying both numbers: $1,330 of fixed overhead (F5) versus a full nut of $4,780 (F6). Overhead alone needs 1.38 jobs (F28); the full nut needs 7.77 (F29).
Why does the break-even count come out as a fraction?
Because it is a rate, not a schedule. 7.77 jobs a month is the honest answer; you cannot sell 0.77 of a job, so in practice it means eight jobs clears the nut and seven does not. The useful conversion is 2.70 working days between jobs (F31), which is something a calendar can actually hold.
Put your own nut, ticket and hard costs through the same formulas in the free contractor break-even calculator, or keep the whole model — the nut, the break-even count, the ticket floor and the six-month cash curve — in the Contractor Break-Even & Cash Model workbook. Every figure in it was rebuilt in code from the same seed inputs and checked against 50 independently calculated values before release; one disagreement would have stopped the release. If you are still standing the business up, the guide to starting a roofing business covers what has to be true before a break-even model is worth keeping.
Contractor Break-Even & Cash Model
Run the numbers from this guide yourself — free, in the browser, no sign-up. Keep the full workbook if it earns its place.
Educational estimates only. These calculators and workbooks do the arithmetic on the figures you enter; they are general-purpose tools, not financial, investment, tax, legal, lending, insurance or construction advice, and no result is a quote, an offer, or a guarantee of any outcome. Results depend entirely on your inputs and assumptions. Verify anything you intend to rely on with a licensed professional — a CPA, attorney, lender, licensed contractor, or your own agent. WorkbookBarn and Marcos Gil accept no liability for decisions made using these tools. Marcos Gil is a licensed Kentucky real estate agent (License No. 296259) and is not a lender, CPA or attorney.